Great Britain's Licensed Gambling Sector Posts £17.5 Billion GGY in April 2025 to March 2026
Theo Powell · Sep 24, 2026
Great Britain's Licensed Gambling Sector Posts £17.5 Billion GGY in April 2025 to March 2026
Data released for the financial year April 2025 to March 2026 shows Great Britain’s licensed gambling industry achieved a 4.4 percent increase in total gross gambling yield to reach £17.5 billion, while the figure excluding lotteries stood at £13.2 billion after rising 4.7 percent, and observers note the remote sector supplied the majority of that expansion.
Remote Sector Drives Overall Expansion
Remote casino, betting and bingo activities together generated £8.3 billion in GGY, marking a 6.9 percent year-on-year advance that outpaced every other category, and figures indicate online casino games, particularly slots, accounted for the largest share of remote growth while betting and bingo contributed smaller but steady portions. Those who track the industry point out that remote platforms continued to attract customers through convenient access and a wide range of game options, which helped sustain the higher growth rate compared with physical venues.
Land-Based Venues Record Modest Increase
Land-based operations posted a 1.1 percent rise over the same twelve-month period, a figure that reflects slower but consistent performance across betting shops, casinos and bingo halls, and experts highlight that these venues maintained stable customer bases despite competition from online alternatives. The more measured pace of growth aligns with patterns observed in previous years where physical sites experienced gradual rather than rapid changes in yield.
Breakdown of Key Categories
Within the remote market, slots and other casino-style games emerged as the leading contributors, whereas land-based betting shops and arcades showed smaller percentage gains that still added to the overall total. Data from the period also separates lottery activity, which remains outside the core £17.5 billion headline figure, allowing analysts to compare like-for-like performance across the regulated market.
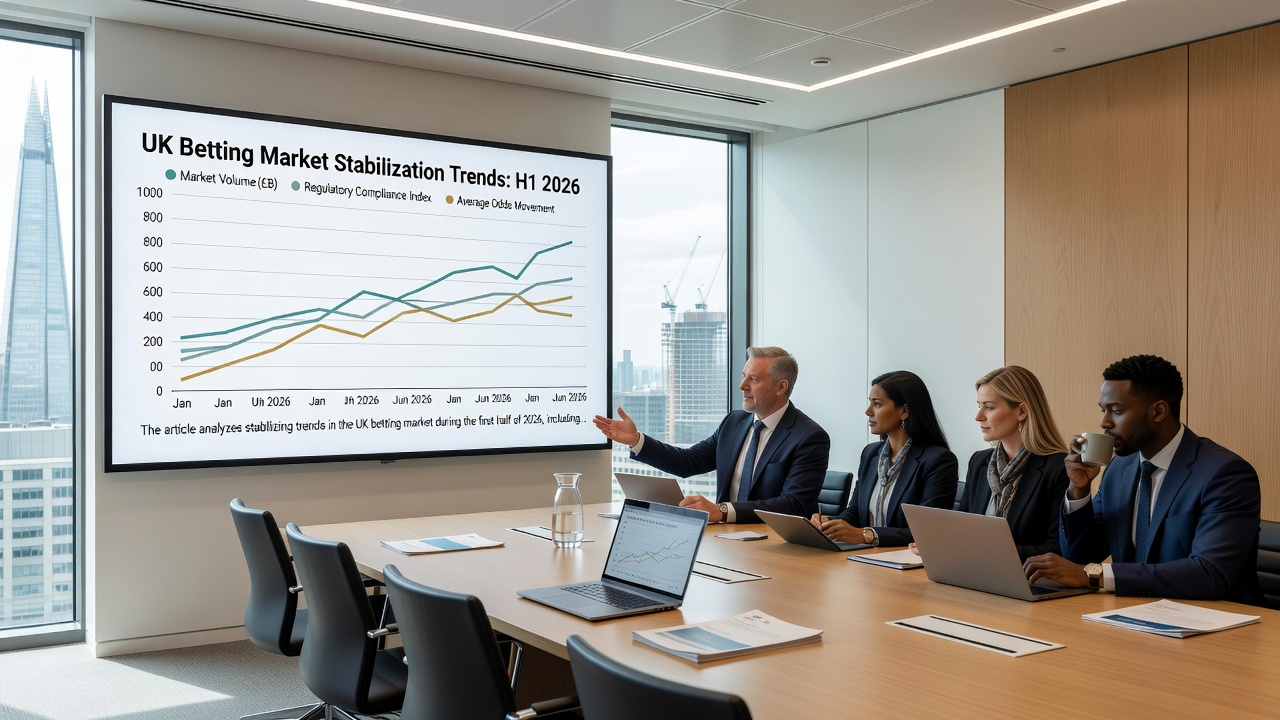
Those reviewing the statistics note that the 6.9 percent remote increase brought the online segment to £8.3 billion, while the 1.1 percent land-based advance kept physical venues on a steady trajectory, and the combination of both produced the reported 4.4 percent overall rise. The Gambling Commission statistics provide the official source for these numbers, covering the full financial year and excluding any unlicensed activity.
Context Around Reporting Timeline
By September 2026 the full set of annual data had been compiled and published, giving operators and regulators a clear picture of performance across the twelve months ending March 2026, and the timing allowed stakeholders to compare results directly with the preceding year without interim adjustments. This reporting cycle follows established practice where year-end figures appear several months after the close of the financial period.
Conclusion
The April 2025 to March 2026 results therefore illustrate a market in which remote channels continued to expand at a faster rate than land-based venues, with online casino games supplying the primary momentum behind the £17.5 billion total, and the separate £13.2 billion non-lottery figure confirming the underlying trend after the 4.7 percent increase. Observers tracking these numbers will watch future releases to see whether the same split between remote and physical performance persists in subsequent periods.